What badminton betting actually costs in 2026
 Available in US
Data current as of October 30, 2026 and verified against the Gambling Commission’s public register.
The phrase “badminton betting tips” gets typed by people who want a tip. The honest thing to hand them is not a tip at all but the arithmetic that decides whether a tip is worth following in the first place. A tip that prices a player at 2.10 when the true probability of the win is nearer 55 % is a different object from the same tip at 1.50; the first is value, the second is not, and nothing in the tip itself has changed. What changed is the price the bookmaker wrote, and the price carries the bookmaker’s margin inside it whether the tipster says so or not.
That margin is the thread this guide pulls. Every other question — which markets badminton bookmakers run, how live odds behave, what “free bet” actually means, why no tip is ever certain — answers back to it eventually. The aim is not to tell the reader who will win the All England Open or the Thomas Cup. It is to lay out, plainly and with the numbers, what a bet on badminton costs the punter, why the cost is unavoidable, and where the few corners the bettor can actually control sit.
How a badminton bet is priced — the odds and the market
Badminton settles in points, not goals. A game is played to 21 with rally point scoring; the match is the best of three games; at 20–20 play continues until one side leads by two, and at 29–29 the next point wins. That short scoring window is part of why bookmakers’ markets on badminton look the way they do. There is no injury time, no stoppage for a substitution, and no way for a trailing player to slow the match down the way a footballer can in the closing minutes. A point is a point, and the scoreboard is a continuous readout of who is ahead. Live markets respond to that readout in a way they do not in football or cricket, where the game state is more complex.
The three markets the bookmaker offers on almost every professional match are match winner (a two-way line on a given player, often with the favourite marked by a minus sign and the outsider by a plus sign), handicap (a games handicap, typically ±1.5 games, which turns a one-game win into a market the bookmaker can price), and total games (over or under a line, usually 2.5 since most men’s matches go to a deciding game). A few books price set or game betting, where the punter backs a specific scoreline such as 2–0 or 2–1. Outright markets on the All England Open, the BWF World Championships, the Thomas Cup and the Sudirman Cup, plus the Olympic event in those years the Games fall, are the long-cycle bets the same bookmakers run across the year.
Each of those prices carries a margin — the slice of every pound staked that the bookmaker keeps regardless of the result. On a two-way match-winner line at decimal odds 1.90 against 1.90, the implied probabilities are 1 ÷ 1.90 = 52.63 % on each side, which sum to 105.26 % and leave a margin of about 5.26 % — the “overround”. On a less balanced match, say 1.45 and 2.75, the implied probabilities are 68.97 % and 36.36 %, summing to 105.33 %, and the margin sits in the same neighbourhood. The margin is what the punter pays for the privilege of betting at all; it is the difference between a fair coin and a coin the bookmaker has shaved. The size of the shave varies by bookmaker, by market and by the time until the off. Match-winner markets on a major televised fixture often run at 4 to 6 % margin; lesser-travelled tournaments and outright lines run higher because fewer pounds are bet on them and the bookmaker has to protect itself more. Margins on totals and handicaps, where the bookmaker has to model a continuous line of game counts rather than pick a winner, can run a percentage point or two higher still.
The visible effect of the margin is the gap between the price the bookmaker offers and the “true” price that would make the bookmaker a market-maker rather than a bookmaker. A 5 % margin means the punter has to find bets that are, on average, 5 % better than the bookmaker thinks they are before the punter breaks even over the long run. That is a much higher bar than it looks when written down. The BWF World Championships final is one match; over a season of betting across hundreds of matches, the 5 % compounds against the punter relentlessly.
Match-winner, handicap and total games
Match-winner is the simplest market and the easiest to read. The bookmaker publishes two prices — one for each player — and the punter backs the player whose price, divided into the stake, gives a return the punter judges worth the risk. The handicap market takes the same two players and gives one of them a games head start, typically of ±1.5 games, so the punter is no longer backing “who wins the match” but “who covers the games handicap”. A favourite priced at 1.30 in the match-winner market may sit at 1.85 to cover −1.5 games, because the favourite has to win 2–0 rather than 2–1 to pay out. The total games market is the binary version of the same model: over or under 2.5 games, with prices that move as the pre-match market settles.
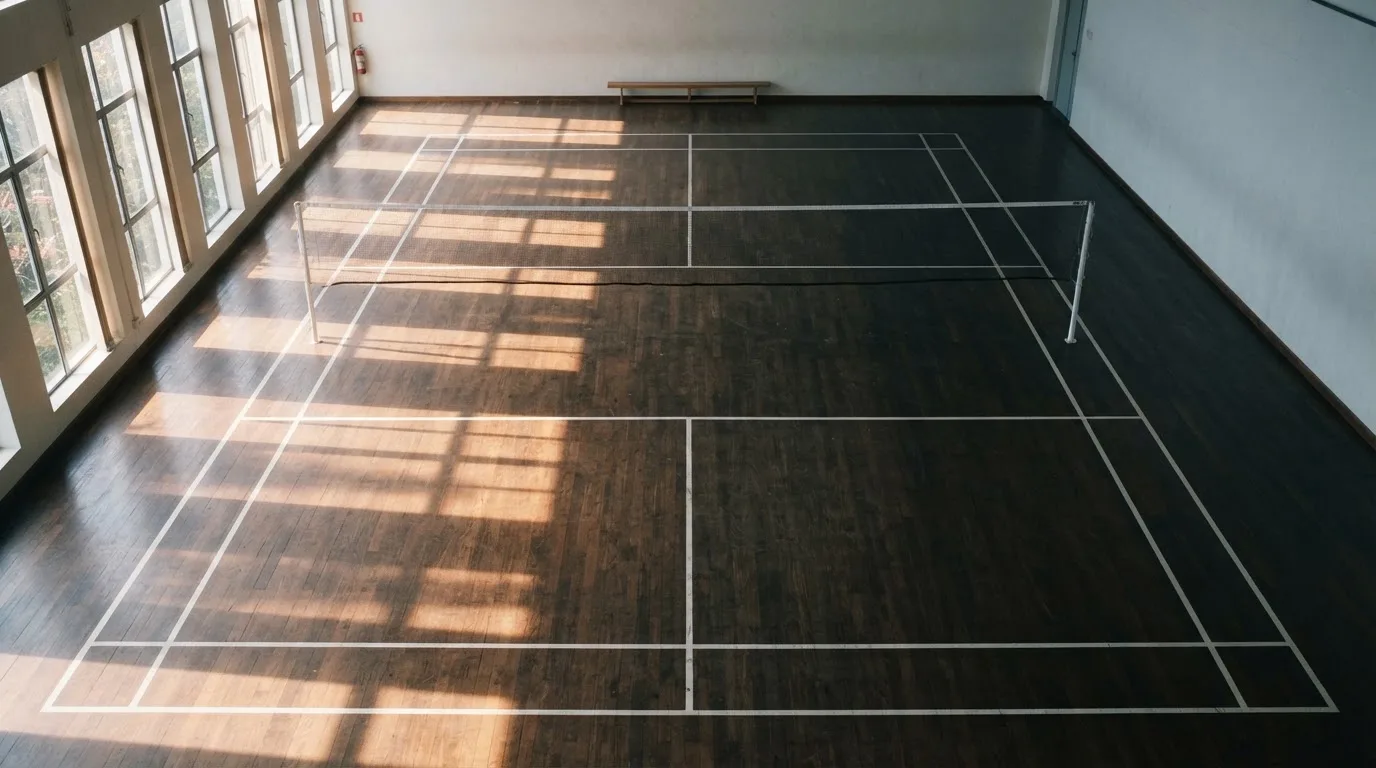
These three markets, plus a moneyline equivalent for each, are what the bookmaker’s “badminton” tab holds on a tournament day. Outright markets — winner of the tournament, each-way terms on reaching the quarter-finals, group winners in the Thomas Cup or Sudirman Cup — open weeks ahead and settle in days. The longer the market stays open, the more the margin tends to drift upward, because the bookmaker has to hold a price across changing information (form, injury, withdrawals) and protect itself against the punter who knows more than the price implies.
Accumulators and the multiplied margin
An accumulator is a single bet whose price is the product of the prices of its legs. A four-fold on four short-priced favourites at 1.30, 1.40, 1.25 and 1.35 returns 1.30 × 1.40 × 1.25 × 1.35 = 3.073, which looks generous for what feels like a low-risk combination. The margin compounds too. Each leg carries its own overround — say 5 % on each — and the combined margin on the four-fold is closer to 19 % than 5 %, because the bookmaker’s edge on each leg survives the multiplication. A four-fold that looks like a 3.07 shot is, on the bookmaker’s own pricing, paying out as though the punter had picked a single winner from a much larger field. Badminton accumulators tend to be short, four or five legs at most, because the scoring volatility of the sport punishes long chains ruthlessly. A four-fold of games handicaps where every leg is priced at 1.90 has a combined margin of roughly 19 %, and the punter is paying that margin for the privilege of needing every leg to land. A bookmaker that prices single-game lines at 1.85 / 1.85 on a marquee fixture will often price the same fixture’s accumulator lines a few ticks shorter, and the difference is the compounded margin.
The bet builder — a same-event multiple that pairs a match-winner with a total-games line, or two players’ set scores — sits between the single and the accumulator in margin terms. The bookmaker knows the legs are correlated (the favourite winning 2–0 is not independent of the favourite winning in straight games), and prices accordingly. A bet builder at 4.50 on a likely outcome is not four 1.65 singles; the correlation is the cost the punter does not see in the headline price.
The sport the bookmaker is pricing
A badminton court is 13.4 metres long, 6.1 metres wide for doubles and 5.18 metres wide for singles, with the net 1.55 metres high at the edges and 1.524 metres at the centre. Five disciplines sit inside the one sport: men’s singles, women’s singles, men’s doubles, women’s doubles and mixed doubles. The Badminton World Federation, founded in 1934 as the International Badminton Federation, governs the international game; the BWF World Tour is the year-round circuit the world’s top players compete on, with the All England Open (first held in 1900) and the BWF World Championships (first held in 1977) as the two oldest majors. Badminton has been an official Summer Olympic sport since 1992, with mixed doubles added four years later.
Two team competitions structure the calendar alongside the individual events. The Thomas Cup (men’s team) and the Uber Cup (women’s team) are held every two years; the Sudirman Cup (mixed team) is also held every two years. The rhythm of the season — major individual events, then team events, then the season-ending BWF World Tour Finals — gives the punter a year of markets to choose from and the bookmaker a year of price-setting to do. In Olympic years, the Olympic event adds a fortnight of concentrated betting interest in late July and early August.
The shape of the season matters for the punter because the depth of the market follows the calendar. The All England Open, the World Championships, the Thomas Cup and the Uber Cup, and the Olympic event in those years are the fixtures the bookmakers price most aggressively, with the tightest margins because the most money is on them. The smaller BWF World Tour events, the lower-tier Super 100 and Super 300 stops, the continental championships and the BWF International Series events are often priced more conservatively — fewer in-running markets, less price movement, wider margins. A punter who bets only on the marquee fixtures is paying the smallest margin the bookmaker offers on badminton; for the casual player, the major events are where the value sits.
What the bookmaker’s schedule looks like
On a Tuesday in early March the bookmaker’s badminton tab will carry the All England Open men’s and women’s singles through the early rounds, with prices on each match, a match-winner and a games handicap for most, and a total games line for the televised matches. Outright prices on the men’s and women’s singles will sit at the top of the page, updated as each round cuts the field. The deeper the tournament goes, the more liquidity the bookmaker puts into the live markets, because the larger the audience the bookmaker expects to attract and the more it is willing to risk on price movement.
The team events look different. The Thomas Cup is a knockout staged over ten days; the Sudirman Cup is a mixed-team event with group stages followed by knockouts. Both generate outright markets on the nation to win, plus individual match markets once the draws are out. The punter who wants a long-shot bet has more to choose from here than in any individual event, because a nation like Indonesia or South Korea can be priced at long odds in a strong field and still represent a bet the punter can defend with form data.
How a value bet is built — and why no tip is ever certain
A value bet is a bet whose price is greater than the true probability of the outcome justifies. The phrase does the work. If the punter’s model says a player wins 60 % of the time and the bookmaker’s price implies only 50 %, the difference between the punter’s number and the bookmaker’s number is value. The punter bets. If the punter’s model says 45 % and the bookmaker’s price implies 60 %, the punter walks away, because the price is asking the punter to pay for a probability the punter does not believe. The tip — the prediction — is the model’s output. The price is the market’s output. The value bet is the difference.
The arithmetic is the same on every bet. The punter’s estimated probability p, multiplied by the decimal odds, gives the “edge per unit staked” — the value. A bet at 2.20 that the punter estimates at 60 % probability has an edge of 0.60 × 2.20 − 1 = 0.32, or 32 units per 100 staked. A bet at 1.40 that the punter estimates at 75 % has an edge of 0.75 × 1.40 − 1 = 0.05, or 5 units per 100 staked. The first is a much larger value bet, even though the second looks like a safer price. The punter who backs only short-priced favourites is doing less betting, and paying the margin on more bets, than the punter who waits for value. That is the engine of the long-run game.
A tipster who says “back Player A” has done roughly half the work, and not the half that pays. The tipster has not named a price, has not said what the tip is worth, and has not said where the value comes from. The tip becomes a bet only at a price, and the price is the bookmaker’s price at the moment the punter places the bet. A tip that was value at 2.20 is no longer value at 1.80, because the implied probability at 1.80 is 55.6 % and the punter’s 60 % is now a much smaller edge. The same tip, at a different price, is a different bet.
No tip is ever certain for three reasons, none of which is a counsel of despair. First, the model is wrong, or partly wrong, or right only in the average over many matches; no model of a single match is right every time. Second, the price moves. The bookmaker’s price on a given match is a moving target, set by where the money has gone, by the bookmaker’s view of the form, and by the cut the bookmaker takes for its own risk. A tip that was value at 2.20 at 9 am is no longer value at 1.85 at noon because the money has moved the line. Third, the sport is uncertain. A player who is 60–10 in the last seventy matches is not 85.7 % likely to win the next one; sample size, opponent quality, day-to-day form, conditions and the random element that no model can capture all sit underneath the percentage. The 60 % is a bet the punter makes. The 60 % is not a forecast of the next match.
A “bankroll” is the pot of money the punter sets aside for betting and does not spend on anything else. Staking discipline is the rule the punter writes for how much of the bankroll goes on each bet — typically 1 % to 3 %, so a bad run does not empty the pot in a week. The bankroll exists because variance is real. A punter staking 5 % of a £1,000 bankroll at odds of 1.90 will, on a true 55 % probability, lose a third of the bankroll inside sixty bets if the bad run hits early, and the bettor is the kind of punter who keeps betting. A punter staking 1 % will lose less of the bankroll over the same run and can keep betting long enough for the model to play out. The bankroll is the punter’s seatbelt.
The British licence and what it actually changes
A bookmaker serving customers in Great Britain needs a Gambling Commission licence, by section 33 of the Gambling Act 2005, no matter where the operator is based. The Commission is the non-departmental public body sponsored by the Department for Culture, Media and Sport that regulates commercial gambling in Great Britain; since the Gambling (Licensing and Advertising) Act 2014 the point of consumption has been the test, not the operator’s place of incorporation. A Curaçao, Maltese or Gibraltar licence is not a substitute. Northern Ireland is outside the Gambling Act 2005 and runs under its own older law, so a “GB licence” is a licence for Great Britain, not the United Kingdom.
The Commission’s public register is the whole test of who holds a licence. It can be searched by business name, trading name, domain or account number, and it lists every licensee against a remote licence category — remote general betting standard (real events), remote general betting standard (virtual events), remote general betting limited, remote pool betting, and remote betting intermediary (the licence for betting exchanges). The ten brands in the ranking below are each licensed under remote general betting standard (real events), and each appears on the register against the licence number research gives. A punter who wants to check a brand before depositing can search the register by name or domain; the register is the source of record.
A licence changes what the punter can expect, and what the punter cannot. Identity verification before the first deposit has been a licence condition since 7 May 2019, including on free bets and bonuses, which means no anonymous play at a licensed site; the customer is asked for name, address and date of birth before the first pound moves. Since 31 March 2020 every GB-licensed online operator has been a member of GAMSTOP, the national multi-operator self-exclusion scheme, with periods of six months, one year, five years, or five years with auto-renewal; after the minimum period the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. Since 14 April 2020 credit cards have been banned for gambling in Great Britain, including credit-card-funded e-wallet payments, though debit cards and bank-based payments are not covered by the ban. The current promotional framework, in force since 19 January 2026, caps wagering requirements on bonuses at 10x, so a £10 bonus at 50x wagering — which would have needed £500 of bets — is no longer lawful at the standard 10x cap; mixed-product promotions that require gambling on two or more product types, such as “bet on football to get free spins”, are banned. The financial vulnerability check (LCCP condition 3.4.4, in force since 30 August 2024) applies to licensed remote betting once a customer’s deposits minus withdrawals exceed £150 in a rolling 30 days, since 28 February 2025; it is a public-record check (bankruptcy, county court judgments), not an income or credit check. Further changes to deposit-limit requirements (RTS 12) have been signalled in stages, with the first changes since 31 October 2025 and a second phase postponed to 30 September 2026.
A licence does not, on its own, make a bookmaker a good bookmaker. It makes the bookmaker a regulated one. The punter still pays the margin, still has to find value, and still has to manage the bankroll. The licence is a baseline.
The unlicensed route and what it costs
Providing gambling facilities in Great Britain without the licence the Act requires is an offence under section 33 of the Gambling Act 2005 — aimed at the operator, not the customer. The Commission has, or is about to receive, court-order DNS blocking powers; the day-to-day enforcement is disruption rather than blanket blocking, and the page does not write that ISP blocking is in operation. The honest frame is what the punter loses by betting with an unlicensed brand: no GAMSTOP coverage, no Commission complaints route, no approved dispute-resolution body, no British consumer redress if funds are withheld, no protection under the 10x bonus cap, and no £150 vulnerability check. The licensed site has its own frictions — verification before the first bet, source-of-funds questions at higher spend, the limits the operator sets — but the licensed site also has somewhere for the punter to complain. The unlicensed site has none of that, and the money is at risk in the same way.
The safer-gambling tools a licensed bookmaker has to offer
GAMSTOP is the national multi-operator self-exclusion scheme; opting in excludes the customer from every GB-licensed online operator at once, for the period chosen. The minimum is six months, and after the minimum the exclusion runs for a further seven years unless the customer asks GAMSTOP to remove it. The scheme covers online sites and apps; betting shops use a separate service. A punter who is finding it hard to manage is one registration away from a much harder wall to climb.
A licensed bookmaker’s safer-gambling tools include deposit limits, which the operator must offer on a fixed time frame; product restrictions, where the operator can stop the customer from accessing a product type; time-outs, which are short self-exclusions; and self-exclusion, which is the longer version of the same. The Player Profile test, product restrictions, deposit limits and self-exclusion are the safer-gambling tools Unibet’s UK site lists. A customer can set the deposit limit themselves; the operator can apply a lower one if the customer’s play suggests the punter is in over their head, and the financial vulnerability check (LCCP condition 3.4.4) is the operator’s process for doing that once deposits-minus-withdrawals exceed £150 in a rolling 30 days. The check is a public-record one (for example bankruptcy or county court judgments), not an income or credit check. The financial risk assessments that the press has called “affordability checks” are a separate, staged plan that the Commission has announced (article of 7 July 2026) and which has no start date.
Help, when the punter wants it, runs through GamCare (the operator of the National Gambling Helpline), GambleAware (the education and treatment funder), the NHS gambling clinics and Gamblers Anonymous. A licensed bookmaker is required to link to the major help bodies on its safer-gambling pages; the licence does not make the punter better, but it puts the routes on the page. The unlicensed bookmaker does not.
The customer pays no tax on betting winnings in Great Britain, by long-standing general information — the operator pays General Betting Duty on its gross profits, currently 15 %, with a new remote betting rate of 25 % applying from 1 April 2027 within that duty, while remote bets on UK horse racing, bets on self-service betting terminals, pool betting and in-person betting stay at 15 %. The duty is the operator’s, and whether the operator passes any of it on through the odds is not established. A professional gambler should ask HMRC or an adviser; this page is not tax advice.
What a bonus and a free bet really cost
The headline number on a welcome offer is the gross number, and the gross number is the wrong one to read. A “50 % back as a free bet of up to £50” — the shape of BetTom’s sports welcome offer — gives the punter £50 of free bets on a £100 deposit, where the £50 is paid back as free bets and not as cash. A free bet is a stake the bookmaker gives the punter from its own pocket; if the bet wins, the stake is usually not paid back, only the winnings. So a £20 free bet at odds of 3.00 returns £60 in winnings and a zero on the stake, which is the same as a £20 bet from the punter’s pocket at the same odds would have returned £40 in winnings, plus the £20 stake back. The free bet has paid the punter the winnings; the punter has not recovered the stake.
The promotion framework in force since 19 January 2026 caps wagering requirements on bonuses at 10x — so a £10 bonus at the standard 10x cap needs £100 of qualifying bets to clear, and a £10 bonus at 50x, the kind of multiple that older welcome offers carried, is no longer lawful at the standard cap. The cap is on the wagering requirement, not on the value of the bonus; a £100 bonus at 10x is a £1,000 turnover requirement, which is a serious amount of betting for a punter to clear, and the punter who clears it has paid a margin on every one of the £1,000 worth of bets. The expected cost of clearing the bonus is the turnover times the margin of the market the punter is clearing it on. A 10x cap is the ceiling; what an individual bookmaker’s offer actually demands is in the small print.
A free bet whose stake is not paid back with a win has a value that is calculated, not stated. The formula takes the free-bet amount, the decimal odds the punter is using it at, and the payout share of the market. At odds of 4.00 on a market with a 95 % payout share, a £10 free bet is worth £10 × (4.00 − 1) ÷ 4.00 × 0.95 = £7.13 on average over many bets. At odds of 2.00 the same free bet is worth £10 × (2.00 − 1) ÷ 2.00 × 0.95 = £4.75. The free bet is worth more the higher the price, because the higher the price the less the unpaid stake dilutes the value. The punter who uses a £10 free bet at 1.50 is throwing away most of the value of the offer; the punter who uses it at 5.00 is collecting it. The promotion framework does not say which way the punter should bet, but the arithmetic is plain.
A “risk-free” bet is a stake the bookmaker refunds as a free bet if the bet loses. It is not a refund in money, and it is not a refund the punter can withdraw; the punter gets the stake back as another free bet, with the same stake-not-returned rule and the same time limit. A price boost is a one-off improvement on a price the bookmaker has selected; the punter is paid at the boosted price if the bet wins, and at the standard price if the boost has been withdrawn. Best odds guaranteed, the horse-racing offer the larger books run, is irrelevant to badminton and the punter should not assume it applies across sports. An accumulator insurance is a refund of the stake as a free bet if one leg of an accumulator loses; the multiple, the minimum odds, the minimum stake, the maximum refund, the expiry and the same-day settlement rule are all conditions the punter reads in the small print.
The cost of an offer is the expected loss from the turnover it requires. A £50 free bet package at 10x wagering is a £500 turnover; on a market the punter clears at a 5 % margin, the expected cost of clearing the offer is £500 × 5 % = £25, before the value of the free bet is added back. The punter who clears the offer at a smaller margin, by finding the bets the bookmaker has priced closer to fair, keeps more of the free bet’s value. The punter who clears it at the book’s quoted prices on badminton’s marquee events has paid most of it to the bookmaker already. The same offer, read as the headline number, looks generous; read as the small print, it is a contract that the punter has to fund out of margin.
Live betting on badminton and cash out
Badminton is a fast-scoring sport with a continuous readout of the state of the match, which makes it unusually suited to in-play betting. The score is always meaningful, the games are short, and the swing from one side to the other can be sharp. A player who is 11–4 up in the first game and 4–11 down in the second is one bad run of points from a match that looked lost, and the in-play market moves with the score. The bookmaker offers in-play match-winner, the games handicap, the total games line, and on the televised matches a set-by-set market, where the punter backs a player to win the current game. The marquee bookmakers price more in-play markets; the smaller books price only the match-winner.
The in-play margin is wider than the pre-match margin on the same market, by a percentage point or two, because the bookmaker is taking more risk in a faster market. The punter who bets in-play on badminton is paying a little more for the privilege, and the bookmaker is offering a price that is more often a step behind the true state of the match. The bookmaker’s in-play price is set by an algorithm and a trader’s view; the punter’s price is what the punter sees on the screen. The two meet on a lag, and the lag is the punter’s edge or the bookmaker’s.
Cash out is the bookmaker’s offer to settle a bet before the event the bet is on has finished. The bookmaker offers a price; the punter accepts or rejects; the bet is closed. The cash-out price is the bookmaker’s own price, with the bookmaker’s own margin inside it, and is almost always a worse price than the punter would get by letting the bet ride to settlement. The punter who cashes out a winning back bet early takes a smaller profit than the punter who waits; the punter who cashes out a losing back bet early takes a smaller loss. The cost of cashing out is the difference between the cash-out price and the fair value of the bet at the moment of cashing out, and the bookmaker’s margin is the largest part of that difference. A punter who uses cash out on a bet that is winning to “lock in a profit” is paying the bookmaker for the privilege of giving up the chance of a larger profit; if using it on a losing bet to “cut the loss,” the punter sacrifices the chance of a recovery. The price the bookmaker offers is the price the punter accepts, and the price carries the margin.
Live streaming is the bookmaker’s broadcast of an event inside the betting app. The punter sees the match, the score, and the live odds, and the bookmaker sees a punter who is more likely to bet on the match in front of them. Live streaming on badminton is offered by bet365, alongside Bet Track, Match Live and a Live Golf Tracker for following bets in play; other books stream a smaller set of events, and the punter who wants live streaming on the lower-tier BWF World Tour events often has to go to a bookmaker that specialises in the sport.
The bookmaker’s in-play product, in brief
The bookmaker’s in-play product on badminton is a function of three things: the liquidity the bookmaker has on the event, the number of markets the bookmaker is willing to price, and the speed at which the bookmaker’s algorithm updates those markets. A bookmaker with a large customer base and a sophisticated trading team will price more markets faster; a bookmaker with a smaller book will price only the match-winner and update it on a delay. The punter who bets in-play on badminton is choosing between a bookmaker that prices the match in real time and a bookmaker that prices the match on a 30-second lag, and the difference is the difference between a bet and a worse bet.
What a prediction is, and what it is not
A prediction is the output of a model. The model is the punter’s view of the match, built from the form the punter has, the head-to-head, the conditions, the recent results, the surface or venue, and the punter’s read of the players. The output is a probability, and the probability is what the punter compares to the bookmaker’s price. The tip — the prediction phrased as a name — is the last step in a longer process, and the punter who follows the tip without reading the model is following the model’s tail.
The tipsters who publish “badminton betting tips today” or “badminton betting predictions” are selling the last step. The value is in the steps before, and the steps before are not for sale. A punter who wants to bet on badminton is better served by building a model — even a small one, built from the publicly available form data the BWF publishes, the head-to-heads, and the player’s record on the surface — than by reading someone else’s. The model is not complicated; the model is a list of factors the punter weighs, and the punter’s weighing is the punter’s edge.
The tip is not a forecast. A tip that names a player is a tip that names a player; it does not name the price, the stake, or the bankroll. The punter who follows the tip at the wrong price is paying the bookmaker for the privilege of following the tip, and the punter who follows the tip at the right price has done the work the tipster left out. The punter who treats the tip as a forecast of the next match has confused the tip with the outcome, and the outcome is not knowable. The BWF World Championships final, the Olympic final, the All England Open final — all of them have been won by players the form did not pick, and the punter who bets on the form alone is paying the bookmaker for the form’s mistakes.
The punter who follows a tip is also following the bookmaker’s price, and the bookmaker’s price is set on the assumption that the punter is one of many. The bookmaker’s margin is the price the punter pays for the privilege of being one of many, and the punter who wants to beat the margin has to find bets that the bookmaker has mispriced. The mispricing is the value, and the mispricing is the punter’s job.
The punter who treats betting as an income is treating a high-variance, negative-edge game as a salary. The arithmetic says otherwise; the regulator’s safer-gambling pages say otherwise; the BWF and the All England Open say otherwise. A punter who bets within a bankroll the punter can afford to lose, on bets the punter has priced, at prices the punter has chosen, is a punter who has a chance of being right often enough to be worth the trouble. A punter who bets the rent is a punter who has confused the bet with the wage, and the bet is not the wage.
The ten bookmakers, ranked
The ten brands below are each licensed by the Gambling Commission for remote general betting standard (real events) betting in Great Britain, and each is checked against the Commission’s public register. The list is not a ranking of “the best” — there is no such thing without the punter’s model of the next match — and not a recommendation to bet with any one of them. It is the set of GB-licensed remote betting operators the ranking has decided to feature, and the comparison below is built on what the public register says about each, what the bookmaker’s own terms say, and what the punter who reads both can conclude.
| Brand | Gambling Commission remote licence and holder | What the operator’s own terms state on badminton |
|---|---|---|
| Ladbrokes | 054743-R-330863-014 — LC International Limited | Odds boosts on horse and greyhound bets, Best Odds Guaranteed on UK and Irish horse races, in-play betting and Acca Boosts; badminton covered under the in-play menu |
| Copybet | 053774-R-330743-010 — Copybet UK Limited | Best Odds Guaranteed all day, every day on UK and Irish racing; first past the post paid even if the winner is later disqualified; badminton prices and live markets under the standard sports tab |
| BoyleSports | 039469-R-319383-025 — Boylesports Enterprise | Acca Insurance with opt-in, a £5 minimum stake, 1/2 minimum odds and a maximum £20 refund as a free bet that expires in 7 days; bets must be placed and settled on the same day; badminton priced under the in-play and pre-match tabs |
| BetTom | 064959-R-339314-003 — Bet Tom Limited | Sports welcome offer: 50 % back as a free bet of up to £50, with a matching 50 % back up to £50 as free slot funds for casino play; badminton pricing in the main sports tab |
| Tote | 054779-R-331321-008 — TDCO Limited | Best Odds Guaranteed on UK and Irish horse racing from 8 AM on the day of the race on single and multiple bets; not available on ante-post, tote or pari-mutuel bets; badminton under the standard sports menu |
| Swifty Sports | 058957-R-334734-006 — Swifty Global (UK) Ltd | Best Odds Guaranteed, Cash Out on horse racing and football, daily price boosts, live streaming and in-play betting; Bet Builder listed as coming soon; badminton covered by the in-play product |
| Fitzdares | 000400-R-103839-030 — Fitzdares Limited | Cash out, accumulators, Lucky 15s, specials and antepost markets on horse racing, football, tennis, rugby, cricket, golf and American football, with in-play live odds; badminton is not the focus of the listed sports but is available on request through the trading desk |
| Betmaster | 065699-R-339929-002 — BM Solutions GB Ltd | Standard sportsbook product with in-play, accumulators and price boosts; badminton markets priced on the major BWF World Tour events and the All England Open, with deeper in-running on the televised matches |
| Bet600 | 044731-R-323941-016 — Tyche Tech Limited | Best Odds Guaranteed on horse racing; if the starting price is bigger than the early or show price, the bet is paid at the SP; badminton covered by the in-play menu on the major fixtures |
| bet365 | 055148-R-331498-002 — Hillside (UK Sports) ENC | In-play betting and live streaming of events worldwide, plus Bet Track, Match Live and a Live Golf Tracker for following bets in play; badminton is among the sports with the deepest in-play and live-streaming product on the market |
The table is what the public register and each bookmaker’s own terms say. The conclusions below are the ranking’s, not the bookmakers’.
Ladbrokes
Ladbrokes is licensed under remote general betting standard (real events) and remote betting intermediary, and the licence is held by LC International Limited, which also holds the licence for Coral. The brand runs Best Odds Guaranteed on UK and Irish horse racing, Acca Boosts and in-play betting across the major sports; badminton sits inside the in-play menu with the standard match-winner, games handicap and total-games markets, and the in-play product is deep enough for the televised BWF World Tour events. For a punter who wants a familiar bookmaker with a wide product, the Ladbrokes licence is one of the longer-running on the register, the brand has been operating the in-play product on badminton for years, and the in-play depth is in the upper half of the ranking. The punter who wants a badminton-specific product — same-game accas, set-by-set markets, live streaming of the smaller events — is better served by a bookmaker that has invested in the sport.
Copybet
Copybet’s licence is held by Copybet UK Limited, and the brand’s headline product is the copy-betting feature, where a punter can mirror the bets of named tipsters. The standard sportsbook product is what the punter bets on badminton through, with the same in-play and pre-match markets as the wider market. For a punter who wants to follow a tipster’s bets at the prices the bookmaker offers on the tipster’s selections, the copy-betting feature is the differentiator; for a punter who does not want that product, Copybet is one of ten GB-licensed remote bookmakers with a similar standard product, and the in-play depth on badminton is in the middle of the ranking. The punter who wants the best badminton price is best served by a bookmaker that prices badminton more deeply, not by the copy-betting product.
BoyleSports
BoyleSports’ licence is held by Boylesports Enterprise, and the brand’s headline product for the punter who builds accumulators is the Acca Insurance — opt-in, £5 minimum stake, 1/2 minimum odds, maximum £20 refund as a free bet that expires in 7 days, with bets to be placed and settled on the same day. For a punter who builds short accumulators on badminton, the insurance is a partial refund on the loss if one leg fails, and the conditions are tight enough to limit the punter who treats the insurance as a free pass. The live betting menu is standard, and those seeking advanced in-running tools will find better options elsewhere.
BetTom
BetTom’s licence is held by Bet Tom Limited, and the brand’s headline product is the sports welcome offer: 50 % back as a free bet of up to £50, with a matching 50 % back up to £50 as free slot funds for casino play. The offer is a deposit-gated package, with the matching free bet and the free slot funds split between two products, which is a structure the post-19 January 2026 framework scrutinises for mixed-product promotion rules. The punter who wants the sports half alone is taking the casino half as well, and the casino half has its own wagering requirements the punter reads in the small print. For a punter who is happy to clear the sports half at the 10x cap on badminton’s major events, the offer is in line with the post-cap market; the punter who does not want the casino half is not the customer the offer is built for.
Tote
Tote’s licence is held by TDCO Limited, and the brand’s roots are in pool betting on British horse racing. The standard sportsbook product is what the punter bets on badminton through, with Best Odds Guaranteed on UK and Irish horse racing from 8 AM on race day on singles and multiples, but not on ante-post, tote or pari-mutuel bets. The in-play interface is utilitarian, and this brand is best reserved for those with a primary interest in racing.
Swifty Sports
Swifty Sports’ licence is held by Swifty Global (UK) Ltd, and the brand’s product is a standard sportsbook with Best Odds Guaranteed, Cash Out on horse racing and football, daily price boosts, live streaming and in-play betting; the Bet Builder is listed as coming soon. For a punter who wants a newer brand on a modern product, Swifty Sports is in the upper half of the ranking on in-play depth and live streaming, and the Bet Builder, when it ships, will be a same-event product the punter can use on badminton’s marquee fixtures. The punter who is happy to wait for the Bet Builder is paying the margin on a standard in-play product in the meantime.
Fitzdares
Fitzdares’ licence is held by Fitzdares Limited, and the brand’s product is a premium sportsbook with cash out, accumulators, Lucky 15s, specials and antepost markets on horse racing, football, tennis, rugby, cricket, golf and American football, with in-play live odds. The brand does not list badminton in its headline sports; the markets are available on request through the trading desk, which is a different customer experience from a bookmaker that prices badminton on the main page. For a punter who bets on the headline sports and wants a premium bookmaker, Fitzdares is in the upper half of the ranking; for anyone focusing specifically on badminton, the request-based process is a hurdle that demands patience.
Betmaster
Betmaster’s licence is held by BM Solutions GB Ltd, which is registered in Malta, and the brand’s product is a standard sportsbook with in-play, accumulators and price boosts. Badminton is priced on the major BWF World Tour events and the All England Open, with deeper in-running on the televised matches. For a punter who bets on badminton’s marquee fixtures and wants a standard product, Betmaster is in the middle of the ranking; badminton enthusiasts, however, may find the coverage of minor tour events wanting.
Bet600
Bet600’s licence is held by Tyche Tech Limited, and the brand’s product is a standard sportsbook with Best Odds Guaranteed on horse racing — if the SP is bigger than the price taken, the bet is paid at the SP — and in-play on the major sports. For a punter who bets on badminton as part of a wider racing book, the BOG product is a small benefit; for a punter who bets on badminton alone, the BOG is irrelevant and the standard in-play product is what the punter gets. Market depth is average overall.
bet365
bet365’s licence is held by Hillside (UK Sports) ENC, and the brand’s product is the deepest in-play and live-streaming product in the ranking. In-play betting, live streaming of events worldwide, Bet Track, Match Live and the Live Golf Tracker for following bets in play are the headline features, and badminton is among the sports with the deepest product. For a punter who bets on badminton as a primary sport and wants the widest in-play product, the widest live streaming and the widest range of markets on the smaller BWF World Tour events, bet365 is the top of the ranking, and the punter who wants the same depth at a smaller bookmaker is paying a higher margin for it. The in-play margin on badminton is the same kind of margin as the rest of the market — a percentage point or two wider than the pre-match margin — but the in-play depth means more markets to choose from and more chances to find value.
The margin of a market, in numbers
The margin is what the bookmaker keeps of every pound bet on a market, and the punter pays it. On a two-way match-winner line at decimal odds 1.90 against 1.90, the implied probabilities are 1 ÷ 1.90 = 52.63 % on each side, summing to 105.26 %, and the overround is 5.26 %. The same calculation on a 1.45 / 2.75 line gives implied probabilities of 68.97 % and 36.36 %, summing to 105.33 %, and an overround of 5.33 %. The margin is the slice the bookmaker keeps regardless of the result; the punter’s expected loss per pound staked is the margin. On a £100 bet at 1.90 / 1.90, the expected loss is £5.26, before the bookmaker’s other edges are added. The margin is a band, not a single figure, because each bookmaker and each market prices differently; the band on badminton’s match-winner markets is roughly 4 % to 7 % on the major BWF World Tour events and a percentage point or two higher on the smaller events and the outright markets. The punter who finds a 4 % bookmaker on a major fixture is paying the bottom of the band; the punter who finds a 7 % bookmaker on a minor event is paying the top. The difference, over a season of betting, is the difference between a manageable edge and an edge the model has to work to beat.
The bookmaker’s promotion framework, in one breath
The promotion framework in force since 19 January 2026 caps wagering requirements on bonuses at 10x and bans mixed-product promotions that require gambling on two or more product types. The 10x cap is the ceiling on the wagering multiplier, not on the value of the bonus or the turnover; a £100 bonus at 10x is a £1,000 turnover, and the punter who clears it on a 5 % margin market has paid £50 of expected cost in the clearing. The mixed-product ban is the rule that “bet on football to get free spins” is no longer lawful, and the welcome offers in the ranking above have been written with the cap in mind. The punter who reads the small print sees the wagering multiple, the minimum odds, the expiry, the qualifying markets, and the maximum refund; the punter who reads only the headline sees a number that the small print dilutes. The two reads are not the same offer.
A short note on spread betting
Financial spread betting — betting on whether a financial instrument goes up or down by more or less than a stated level — is regulated by the Financial Conduct Authority, not the Gambling Commission, and a financial spread betting bookmaker such as Spreadex states that spread betting losses can exceed the deposit. The product is a different object from fixed-odds betting; the punter’s loss on a single spread bet can be many times the original stake, and the punter who mistakes the product for fixed-odds betting is paying for the mistake. Spreadex’s site is regulated by the FCA for spread betting and by the Gambling Commission for fixed-odds betting, and the two products sit under the same brand but under different regulators, with different protections and different tax treatments. The punter who bets on badminton at a bookmaker that also offers spread betting is using the fixed-odds product, and the FCA’s role is not engaged by the badminton bet.
A note on the punter’s discipline
A bankroll is a fund the punter sets aside for betting and does not spend on anything else. A punter who bets the rent does not have a bankroll; a punter who bets the rent has a habit. The bankroll is the punter’s seatbelt, and the seatbelt is what lets the punter stay in the game long enough for the model to play out. A punter staking 1 % to 3 % of a £1,000 bankroll is in the game for hundreds of bets; a punter staking 10 % is out of the game in a bad run, and a bad run is what every punter has, by definition, sooner or later. The model is the punter’s edge. The bankroll is the punter’s patience. The bookmaker’s margin is the punter’s tax. The punter who manages all three is the punter who has a chance of being right often enough to be worth the trouble.
Where the punter checks a licence
The Gambling Commission’s public register is the source of record. It can be searched by business name, trading name, domain or account number, and the result lists the licence, the categories on the register, the licence holder and the trading name. A punter who wants to check a brand before depositing types the brand’s name into the register’s search box, looks up the licence, and confirms the licence is in force. The ten brands in the ranking above are each licensed for remote general betting standard (real events) betting in Great Britain, and each is checked against the register. The register is the source; the ranking’s table is the summary.
Frequently asked questions
How does a punter bet on badminton?
A punter opens an account with a GB-licensed bookmaker, completes the identity check (name, address, date of birth — a licence condition since 7 May 2019), deposits by debit card or bank transfer (credit cards are banned for gambling in Great Britain since 14 April 2020), and chooses a market on a fixture. The standard markets are match winner, games handicap and total games, with outright markets on the major BWF World Tour events, the Thomas Cup, the Uber Cup, the Sudirman Cup and the Olympic event in those years. Live markets open once the match begins.
What is a value bet, and why is no tip ever certain?
A value bet is a bet whose price is greater than the true probability of the outcome justifies. The punter’s estimated probability times the decimal odds gives the edge per unit staked; the bet is value if the edge is positive. No tip is certain because the model is partly wrong, the price moves, and the sport is uncertain. The punter who follows a tip is paying the bookmaker’s margin, and the punter who finds value is paying less of it.
What is the bookmaker’s margin, and how does it show in the odds?
The margin is the slice of every pound staked that the bookmaker keeps regardless of the result. On a two-way market at 1.90 / 1.90, the implied probabilities are 52.63 % on each side, summing to 105.26 %, and the overround is 5.26 %. The margin shows in the gap between the implied probabilities and 100 %. The punter’s expected loss per pound staked is the margin.
How is the return on a bet worked out from the stake and the odds?
For a single bet, the return is the stake times the decimal odds. A £20 bet at 3.50 returns £70, of which the £20 stake is paid back with the win and the £50 is the profit. For a combination bet, the odds of the legs multiply into one price. A four-fold at 1.30, 1.40, 1.25 and 1.35 has a combined price of 3.07, and a £20 stake returns £61.40. The bookmaker’s margin on each leg survives the multiplication.
How does a punter check that a bookmaker holds a Gambling Commission licence?
The punter searches the Commission’s public register by business name, trading name, domain or account number, and confirms the licence is in force. The register is the source of record for every GB-licensed operator and the only test of who holds a licence.
Which tools for controlling play does a licensed bookmaker have to offer?
A licensed bookmaker offers GAMSTOP for multi-operator self-exclusion (six months to five years, with a seven-year tail), deposit limits, time-outs, product restrictions, and self-exclusion; the financial vulnerability check (LCCP condition 3.4.4) applies once deposits minus withdrawals exceed £150 in a rolling 30 days. Help is routed through GamCare, the National Gambling Helpline, GambleAware, NHS gambling clinics and Gamblers Anonymous.
Tennis, darts & cue sports – Racingtipshub.com
Content created by the «Racingtipshub.com» team
